How much you need to retire, and the year you reach it
The need
- A year's spending today: ₹6,00,000.
- Grown with inflation for 25 years at 6%: ₹6,00,000 × (1 + 6%)25 = ₹25,75,122 a year.
- Divided by the withdrawal rate: ₹25,75,122 ÷ 4% = ₹6,43,78,061.
That corpus is ₹1,50,00,000 in today's rupees, 25 times a year's spending now. The need is grown with inflation before it is set beside a corpus, so that both are in the rupees of the same year.
The year it is covered
The corpus is ₹10,00,000 today, plus a ₹20,000 a month SIP counted at the start of each month, stepping up 10% a year, all at 10% a year. The need is ₹6,00,000 a year, grown with 6% inflation to each year and divided by 4%:
| Years from now | A year's need then | Corpus needed | Corpus projected | Against the need |
|---|---|---|---|---|
| 5 | ₹8,02,935 | ₹2,00,73,384 | ₹34,61,211 | short by ₹1,66,12,173 |
| 10 | ₹10,74,509 | ₹2,68,62,715 | ₹85,54,887 | short by ₹1,83,07,828 |
| 15 | ₹14,37,935 | ₹3,59,48,373 | ₹1,85,77,973 | short by ₹1,73,70,400 |
| 20 | ₹19,24,281 | ₹4,81,07,032 | ₹3,76,50,849 | short by ₹1,04,56,183 |
| 22 | ₹21,62,122 | ₹5,40,53,061 | ₹4,92,99,252 | short by ₹47,53,809 |
| 23 | ₹22,91,850 | ₹5,72,96,245 | ₹5,62,87,126 | short by ₹10,09,119 |
| 24 | ₹24,29,361 | ₹6,07,34,020 | ₹6,41,79,583 | covered |
| 25 | ₹25,75,122 | ₹6,43,78,061 | ₹7,30,87,659 | covered |
The corpus first reaches the need in year 24: ₹6,41,79,583 against ₹6,07,34,020. This is the financial-independence year: 24 years from now, 1 year before the 25 years the plan was made for. The need grows too, at 6% a year, so the corpus is compared with the need of that year, not today's.
If the withdrawal rate is different
The same ₹6,00,000 a year, 25 years to go, and the same SIP and corpus:
| Withdrawal rate | Corpus needed | Financial independence in |
|---|---|---|
| 3% | ₹8,58,37,414 | 28 years |
| 3.5% | ₹7,35,74,927 | 26 years |
| 4% (Pocket's assumption) | ₹6,43,78,061 | 24 years |
| 5% | ₹5,15,02,449 | 21 years |
If inflation is different
| Inflation | Corpus needed | Financial independence in |
|---|---|---|
| 5% | ₹5,07,95,324 | 21 years |
| 6% (Pocket's assumption) | ₹6,43,78,061 | 24 years |
| 7% | ₹8,14,11,490 | 27 years |
If the SIP is different
₹10,00,000 invested, 10% step-up, the need at 4% and 6% inflation:
| SIP a month | Financial independence in |
|---|---|
| ₹10,000 | 32 years |
| ₹20,000 | 24 years |
| ₹30,000 | 19 years |
What the projection assumes
- One return, 10% a year, on the corpus until the year it is set beside the need, and a SIP paid each month.
- One inflation rate, 6%, for every year, and a need that is spending alone: no tax, no change in what is spent.
- A rule of thumb, not a guarantee. A withdrawal rate of 4% says what share of the corpus is taken in the first year; markets and spending in a particular retirement can differ from the average.
How Pocket works it out
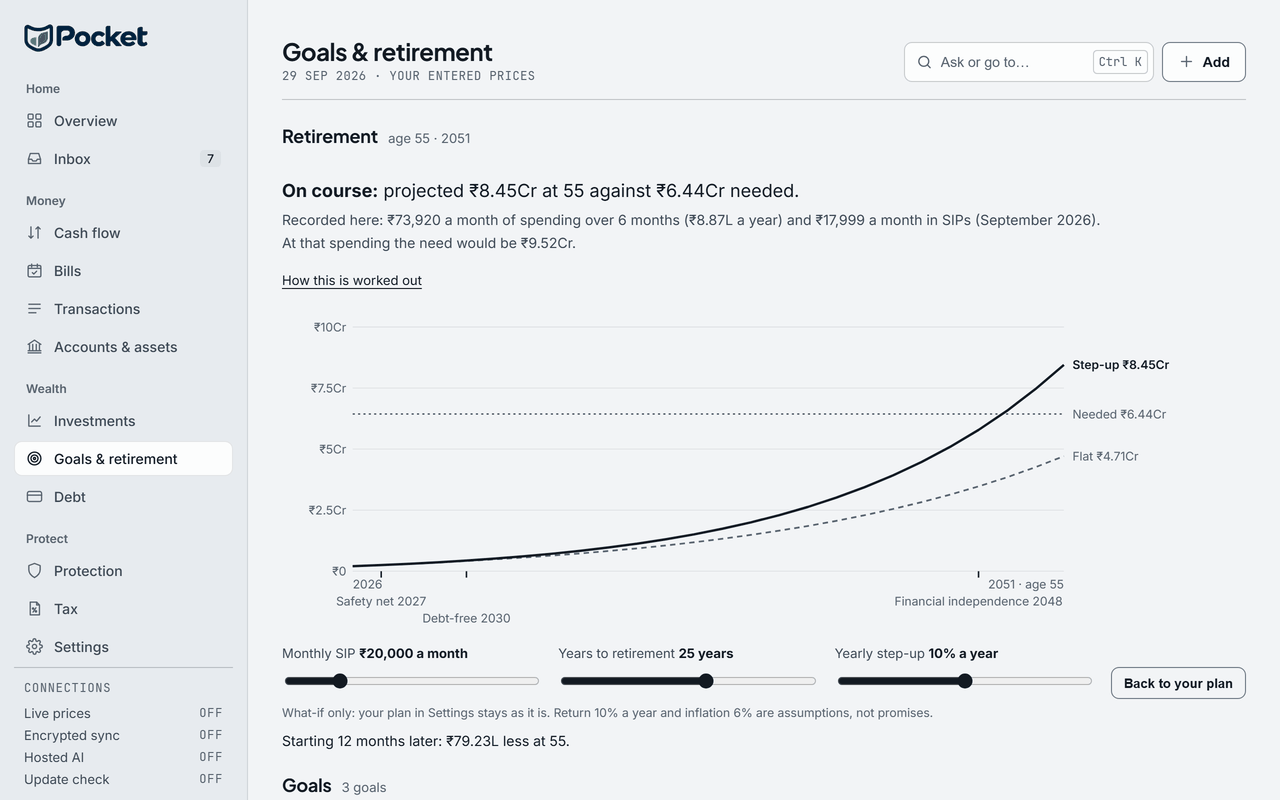
The figures on this page are Pocket's own, from its planning engine when the page was built: the retirement need, the projection of the corpus with a step-up SIP, and the first year it is covered. The Goals page works the same for your annual expenses, years to retirement and SIP, and shows that year as Financial independence.
Questions
How much do I need to retire in India?
Pocket's rule: a year's spending, grown at 6% a year to the day of retirement, divided by a withdrawal rate of 4%. On ₹6,00,000 a year today and 25 years to go, that is ₹25,75,122 a year then and a corpus of ₹6,43,78,061, which is ₹1,50,00,000 in today's rupees: 25 times a year's spending today.
What is the withdrawal rate?
The share of the corpus taken out in the first year of retirement, and then increased with inflation. 4% is a rule of thumb for the 'safe-withdrawal' rate, not a guarantee; the table above shows what the corpus becomes at other rates.
What is the financial-independence year?
The first year in which the corpus, projected with the SIP and its step-up, reaches the corpus that year's spending needs: with the SIP and the need both growing, it can come before the retirement date the plan was made for.
Sources
- Pocket's planning engine: retirement_need (spending grown with inflation, over the withdrawal rate) and fire_year (the SIP counted at the start of each month, the need grown with inflation every year)
Pocket is free on Windows, macOS, Linux and Android, and keeps everything on your own device: download Pocket.