PPF over 15 years, worked through
The rules
- Deposits: at least ₹500 and at most ₹1,50,000 in each financial year (April to March), in multiples of ₹50.
- Interest: worked out each month on the lowest balance between the close of the 5th and the end of the month, and added once a year, on 31 March. Money in by the 5th earns that month's interest; money in on the 6th does not.
- Term: the account matures after fifteen whole financial years from the end of the year it was opened in, and can then be extended in blocks of five years, with deposits or without.
- Rate: set by the Ministry of Finance for each quarter. It has been 7.1% since 1 April 2020; it was 7.9% before that.
- Tax: deposits count toward the old regime's ₹1,50,000 limit under 80C; the interest and the maturity amount are tax-free.
₹1,50,000 a year for 15 years
The most a year, paid in by 5 April so that it earns the whole year's interest, at 7.1% every year:
| Year | Paid in | Balance | Interest that year |
|---|---|---|---|
| 1 | ₹1,50,000 | ₹1,60,650 | ₹10,650 |
| 2 | ₹3,00,000 | ₹3,32,706 | ₹22,056 |
| 3 | ₹4,50,000 | ₹5,16,978 | ₹34,272 |
| 4 | ₹6,00,000 | ₹7,14,334 | ₹47,356 |
| 5 | ₹7,50,000 | ₹9,25,701 | ₹61,367 |
| 6 | ₹9,00,000 | ₹11,52,076 | ₹76,375 |
| 7 | ₹10,50,000 | ₹13,94,524 | ₹92,448 |
| 8 | ₹12,00,000 | ₹16,54,185 | ₹1,09,661 |
| 9 | ₹13,50,000 | ₹19,32,282 | ₹1,28,097 |
| 10 | ₹15,00,000 | ₹22,30,124 | ₹1,47,842 |
| 11 | ₹16,50,000 | ₹25,49,113 | ₹1,68,989 |
| 12 | ₹18,00,000 | ₹28,90,750 | ₹1,91,637 |
| 13 | ₹19,50,000 | ₹32,56,643 | ₹2,15,893 |
| 14 | ₹21,00,000 | ₹36,48,515 | ₹2,41,872 |
| 15 | ₹22,50,000 | ₹40,68,209 | ₹2,69,694 |
By year 15, ₹22,50,000 has gone in and the balance is ₹40,68,209. The interest grows each year because it is added to the balance and earns interest itself: the last five years add ₹18,38,085, more than the whole balance after the first 8 years, ₹16,54,185.
The first two years, worked through
- Year 1: ₹1,50,000 × (1 + 7.1%) = ₹1,60,650.
- Year 2: (₹1,60,650 + ₹1,50,000) × (1 + 7.1%) = ₹3,32,706.
- Each year after: the balance plus that year's deposit, × (1 + 7.1%).
Worked out by the month, as the scheme does, the result is the same for money that is in by 5 April: it sits in the account for all twelve months, and the year's interest is added on 31 March.
Smaller deposits
The same 15 years at 7.1%, for a smaller deposit each year. The balance grows in proportion to the deposit:
| A year | Paid in | After 15 years | Of which interest |
|---|---|---|---|
| ₹12,000 | ₹1,80,000 | ₹3,25,457 | ₹1,45,457 |
| ₹50,000 | ₹7,50,000 | ₹13,56,070 | ₹6,06,070 |
| ₹1,00,000 | ₹15,00,000 | ₹27,12,139 | ₹12,12,139 |
| ₹1,50,000 | ₹22,50,000 | ₹40,68,209 | ₹18,18,209 |
When it matures, and after
The fifteen years count from the end of the financial year the account is opened in. An account opened in the first days of April 2026, in the financial year 2026-27, matures on 1 April 2042, after the years 2027-28 to 2041-42: it takes deposits in sixteen financial years, the year it was opened and fifteen more. With ₹1,50,000 in by 5 April in each of the sixteen, it comes to ₹45,17,702 at 7.1%.
At maturity the account can be closed, or extended for five years at a time. With ₹1,50,000 a year continuing:
| Held for | Paid in | Balance | Of which interest |
|---|---|---|---|
| 15 years (the term) | ₹22,50,000 | ₹40,68,209 | ₹18,18,209 |
| 20 years (one extension) | ₹30,00,000 | ₹66,58,288 | ₹36,58,288 |
| 25 years (two extensions) | ₹37,50,000 | ₹1,03,08,015 | ₹65,58,015 |
If the rate changes
The rate is reviewed every quarter, and a change applies to the whole balance from that quarter. ₹1,50,000 a year for 15 years, if the rate were held at each of these for all fifteen:
| Rate a year | After 15 years | Of which interest |
|---|---|---|
| 6.6% | ₹38,96,480 | ₹16,46,480 |
| 7.1% (the rate now) | ₹40,68,209 | ₹18,18,209 |
| 7.9% | ₹43,60,517 | ₹21,10,517 |
How Pocket works it out
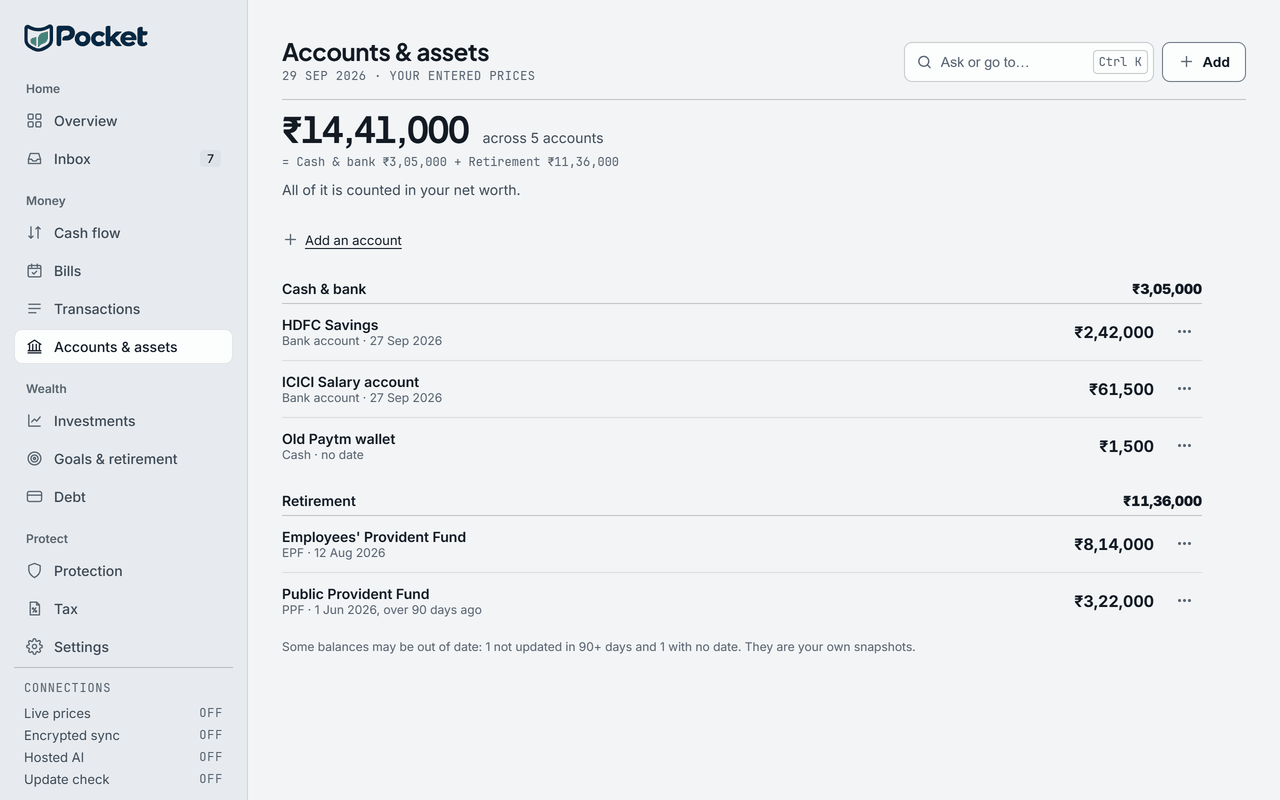
The figures on this page are Pocket's own, from its planning engine's PPF projection when the page was built: each year's deposit at the start of the year, and the year's interest on the balance. In the app, your PPF balance goes in Accounts & assets under Retirement, with the date it stands at, where it counts in your net worth and in the corpus the Goals page projects your retirement from.
Questions
How much can go into a PPF account in a year?
At least ₹500 and at most ₹1,50,000 in a financial year, in multiples of ₹50, in one go or in several deposits. A year with less than ₹500 leaves the account discontinued until it is revived with a fee of ₹50 and ₹500 for each year missed.
When is PPF interest added?
It is worked out for each month on the lowest balance between the close of the 5th and the end of the month, and added to the account once a year, at the end of the financial year. A deposit made after the 5th of a month earns nothing for that month.
What does ₹1,50,000 a year come to after 15 years?
₹40,68,209 at 7.1% a year, if each year's deposit is in by 5 April and the rate stays 7.1%: ₹22,50,000 paid in and ₹18,18,209 of interest. The rate is set by the government every quarter, so the real figure moves with it.
Is PPF interest taxed?
No. The interest and the amount at maturity are tax-free, and deposits count toward the old regime's ₹1,50,000 limit under 80C; the new regime has no 80C deduction.
Sources
- The Public Provident Fund Scheme, 2019 (G.S.R. 915(E), 12 December 2019), under section 3A of the Government Savings Promotion Act, 1873: the deposit limits, interest on the lowest balance after the 5th, its credit at the end of each year, the term and its extension
- The Public Provident Fund (Amendment) Scheme, 2020 (G.S.R. 290(E), 5 May 2020): 7.1% from 1 April 2020
- Ministry of Finance, Department of Economic Affairs, 30 September 2026: small savings rates for 1 October to 31 December 2026, PPF 7.1%
- India Post: the Public Provident Fund account, how it is opened and run
Pocket is free on Windows, macOS, Linux and Android, and keeps everything on your own device: download Pocket.